For millions of salaried employees in India, the word “bonus” evokes thoughts of Diwali festivities, annual appraisals, or performance-driven rewards. However, in corporate payroll and Indian labor jurisprudence, a statutory bonus is fundamentally different from a discretionary incentive: “Am I legally entitled to an annual bonus? How is the statutory 8.33% bonus calculated when my monthly Basic Pay exceeds ₹21,000? Why do IT companies include a monthly ‘Statutory Bonus’ line item in CTC offer letters? What happens to your unpaid bonus if you resign before the annual payout date? Can an employer withhold your bonus during Full and Final (FnF) settlement?” Governed strictly by the Payment of Bonus Act, 1965, statutory bonus is an enforceable legal right designed to share employer profits and bridge the gap between actual wages and a living wage. In this comprehensive 2026 guide, we analyze the exact mathematical formulas for statutory bonus calculation in Indian companies, examine the ₹21,000 wage ceiling, demystify monthly vs annual payout structures, review disqualification grounds, and explain your statutory recovery remedies under Indian labor law.
Quick Summary: Statutory Bonus Realities in India (2026)
Before diving into legal wage ceilings, mathematical formulas, and payroll structuring, review this executive overview of the Payment of Bonus Act provisions:
| Statutory Dimension | Legal Mandate under Payment of Bonus Act, 1965 | Governing Clause | Practical Corporate Implication |
|---|---|---|---|
| Applicability Threshold | Applies to every factory and every establishment employing 20 or more persons (or 10+ where notified by state government). | Section 1(3) | Enforceable across IT companies, private firms, commercial enterprises, and startups once employee count reaches 20. |
| Employee Eligibility Wage Ceiling | Employees earning a Basic Salary + Dearness Allowance (DA) up to ₹21,000 per month are legally entitled. | Section 2(13) | Employees earning above ₹21,000 Basic are outside the mandatory purview, but companies often pay ex-gratia or contractual bonuses. |
| Service Tenure Requirement | Employee must have worked for not less than 30 working days in that accounting year. | Section 8 | Even temporary, contract, or probationary staff who complete 30 days qualify for pro-rata bonus payout. |
| Minimum Statutory Bonus Rate | Strictly mandated at 8.33% of annual eligible wages or ₹100, whichever is higher, regardless of employer profit or loss. | Section 10 | Guaranteed floor payout; equivalent to approximately one month’s eligible basic wage. |
| Maximum Statutory Bonus Rate | Capped at 20% of annual eligible wages, dependent on available “allocable surplus” of the enterprise. | Section 11 | Upper ceiling for statutory claims; payouts above 20% are classified as performance incentives or ex-gratia. |
| Calculation Wage Ceiling | Bonus is calculated on ₹7,000 per month or the State Minimum Wage for the scheduled employment, whichever is higher. | Section 12 | Limits employer financial exposure; statutory calculation is capped even if the employee earns ₹18,000 or ₹20,000 Basic. |
| Statutory Payout Deadline | Must be paid in cash/bank transfer within 8 months from the close of the accounting financial year (by November 30 for April–March fiscal). | Section 19 | Companies typically time disbursement with Diwali/Durga Puja festive cycles in October/November. |
Who Qualifies for Statutory Bonus? Eligibility Criteria Explained
To claim a statutory bonus under Indian law, an employee must satisfy three concurrent legal conditions:
- Establishment Coverage: The employer must employ 20 or more persons on any day during the accounting year. Note that newly established enterprises enjoy a 5-year operational infancy buffer where bonus is payable only in the years they derive derived profits from the manufacture/sale of products.
- Salary Ceiling Threshold: Under Section 2(13), an “employee” means any person (other than an apprentice) employed on a salary or wage not exceeding ₹21,000 per month in any industry to do skilled, semi-skilled, unskilled, manual, supervisory, managerial, administrative, technical, or clerical work. For calculating this ₹21,000 limit, only Basic Salary and Dearness Allowance (DA) are considered; allowances like HRA, Conveyance, Special Allowance, and Medical reimbursement are strictly excluded under our salary structure optimization rules.
- 30 Working Days Rule: Under Section 8, the employee must have worked in the establishment for at least 30 working days in that accounting financial year. Working days include authorized paid leaves, maternity leaves under the Maternity Benefit Act, temporary disablement leaves under the Workmen’s Compensation Act, and statutory holidays.
The Calculation Formula: Minimum (8.33%) & Maximum (20%) Limits
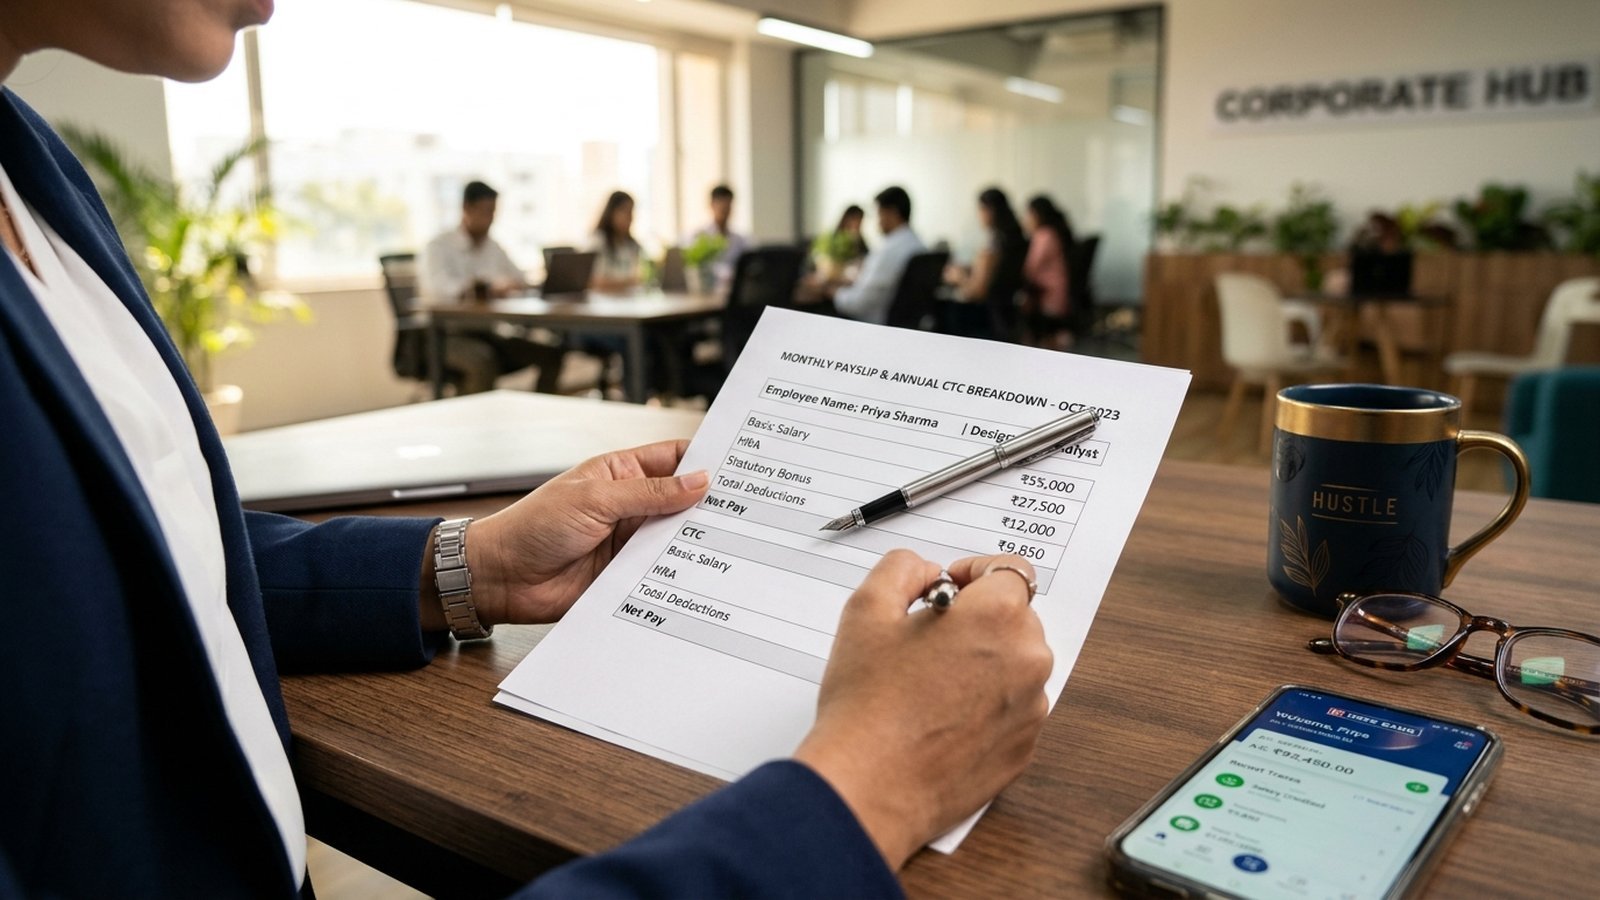
The mathematical computation of statutory bonus is governed by Section 10, Section 11, and Section 12 of the Act. Many employees erroneously assume that 8.33% is multiplied directly against their entire gross CTC. In statutory reality, the calculation involves specific statutory benchmark caps:
The Section 12 Calculation Cap Rule
Under Section 12, where the salary or wage of an employee exceeds ₹7,000 per month (or the minimum wage for scheduled employment fixed by the appropriate government, whichever is higher), the bonus payable to such employee under Section 10 or Section 11 is calculated as if his salary or wage were ₹7,000 per month (or the state minimum wage).
| Employee Basic Salary | Applicable Calculation Base | Minimum Bonus (8.33% Annual) | Maximum Bonus (20% Annual) |
|---|---|---|---|
| ₹6,000 per month (Below ₹7,000) | Actual Basic = ₹6,000/mo (₹72,000/yr) | ₹72,000 × 8.33% = ₹5,998 per year (~₹500/mo) | ₹72,000 × 20% = ₹14,400 per year (~₹1,200/mo) |
| ₹12,000 per month (Above ₹7,000, under ₹21,000) | Capped at ₹7,000/mo (₹84,000/yr)* | ₹84,000 × 8.33% = ₹6,997 per year (~₹583/mo) | ₹84,000 × 20% = ₹16,800 per year (~₹1,400/mo) |
| ₹18,000 per month (Above ₹7,000, under ₹21,000) | Capped at ₹7,000/mo (₹84,000/yr)* | ₹84,000 × 8.33% = ₹6,997 per year (~₹583/mo) | ₹84,000 × 20% = ₹16,800 per year (~₹1,400/mo) |
| ₹35,000 per month (Exceeds ₹21,000 eligibility) | Exempt from Statutory Mandate | Nil Statutory Entitlement (Payable only if specified in corporate employment contract) | Governed by corporate performance appraisal or contractual ex-gratia policy. |
*Note on State Minimum Wages: If the state government where the establishment operates (e.g., Delhi, Maharashtra, Karnataka) has notified a higher statutory minimum wage for clerical or technical categories (e.g., ₹11,500 or ₹14,000/month), that higher figure replaces ₹7,000 as the calculation base.
Why Exactly 8.33%? The Historical Mathematics
Employees often wonder why the Indian legislature chose the unusual fraction of 8.33%. In an accounting year consisting of 12 calendar months, one single month’s salary represents exactly one-twelfth (1/12) of annual earnings:
1 ÷ 12 = 0.08333... = 8.33%
Therefore, paying a minimum statutory bonus of 8.33% effectively guarantees that an eligible employee receives a 13th month of basic wages as a statutory entitlement, irrespective of enterprise profitability.

Why IT Companies Pay “Statutory Bonus” Monthly in Indian CTCs
If you inspect modern IT services appointment letters from firms like TCS, Infosys, Wipro, Cognizant, or tech startups, you will frequently notice a line item labeled “Statutory Bonus / Advance Statutory Bonus” paid out every single month (typically ₹583 or ₹1,400 per month). Why do companies do this?
- Cash Flow & Provisioning: Instead of facing massive liquidity drains during the Diwali festive season in October/November, corporate payroll amortizes the liability across 12 monthly payroll cycles.
- Contractual Compliance: By paying
₹84,000 × 8.33% ÷ 12 = ₹583.33 per month, the employer ensures continuous legal compliance with Section 10, eliminating cumulative year-end liability. - Ex-Gratia Conversion for Higher Earners: For tech employees whose Basic Salary exceeds ₹21,000, companies maintain a “Statutory Bonus / Ex-Gratia” line item in the CTC structure to optimize employer cost allocations and minimize Basic Pay ratios, directly impacting gratuity liability calculations and EPF administrative matching.
Legal Caveat on Monthly Advance Bonus: The Madras High Court and Karnataka High Court have upheld that an employer can adjust monthly advance bonus payouts against the final statutory bonus liability, provided the salary slip clearly itemizes the payment as “Advance Statutory Bonus” and the total annual disbursement meets or exceeds 8.33% of eligible wages.
Disqualification from Bonus: When Can an Employer Forfeit It?
Under Section 9 of the Payment of Bonus Act, an employee is completely disqualified from receiving any bonus under the Act if they are dismissed from service for:
- Fraud: Proven financial embezzlement, falsification of corporate accounts, or fraudulent expense claims.
- Riotous or Violent Behavior: Engaging in physical violence, assault, or disorderly conduct while on the premises of the establishment.
- Theft, Misappropriation, or Sabotage: Stealing company property, sabotaging intellectual property, deleting corporate databases, or destroying manufacturing machinery.
Essential Legal Safeguard: Disqualification under Section 9 is applicable only if the employee has been formally dismissed from service following a domestic inquiry adhering to principles of natural justice. An employer cannot arbitrarily withhold an employee’s bonus simply by making unsubstantiated allegations or placing the employee under a Performance Improvement Plan (PIP).
What Happens to Bonus Upon Resignation & FnF Settlement?
A frequent dispute during employee separation concerns unpaid bonus arrears. If an eligible employee works for 7 months in a financial year and resigns, are they entitled to bonus for those 7 months? Yes, absolutely.
- Pro-Rata Statutory Entitlement: Under Section 13, where an employee has not worked for all working days in an accounting year, the minimum or maximum bonus is proportionately reduced. As long as the employee completed 30 working days, they are legally entitled to pro-rata bonus for the exact number of days served.
- Mandatory Inclusion in FnF: Under the Payment of Wages Act and State Shops and Commercial Establishments Acts, all statutory dues must be settled during the Full and Final (FnF) settlement within 7 to 30 days of the last working day. If the company calculates bonus only at year-end (October/November), they must either disburse estimated pro-rata bonus in the FnF statement or issue a supplementary payment once the annual audit is finalized.
- Notice Period Adjustments: If an employee resigns without serving the contractual notice period and the employer imposes a notice period buyout deduction, the company may adjust accrued bonus arrears against notice pay shortages, but cannot withhold bonus as a punitive penalty.
Taxability of Statutory Bonus: New vs Old Tax Regime
Unlike statutory gratuity, which enjoys tax exemption up to ₹20 Lakhs under Section 10(10), statutory bonus is 100% taxable as “Profits in lieu of Salary” under Section 17(3) of the Income Tax Act, 1961:
- Tax Deduction at Source (TDS): When bonus is disbursed (either monthly or as a lump sum annual payout), the employer adds the amount to your gross taxable income and deducts TDS according to your chosen tax slab, as detailed in our New vs Old Tax Regime guide.
- Form 16 Reconciliation: Ensure that all bonus disbursements are accurately reflected in Part B of your Form 16 and match the tax credits shown in your AIS and Form 26AS, as explained in our Form 16 reconciliation guide.
- Relief under Section 89(1): If you receive delayed bonus arrears from prior financial years in a single financial year resulting in a higher tax bracket, you can claim tax relief by submitting Form 10E on the income tax e-filing portal before filing your ITR.
Frequently Asked Questions (FAQs)
1. Can an employer refuse to pay statutory bonus if the company suffered financial losses?
No. Under Section 10 of the Payment of Bonus Act, the payment of the minimum bonus of 8.33% is mandatory irrespective of whether the employer has an allocable surplus or incurred severe commercial losses in that accounting year. Financial losses only exempt the employer from paying higher bonus rates between 8.33% and 20% under the “Set-On and Set-Off” allocable surplus provisions.
2. Is an employee with a Basic Salary above ₹21,000 legally entitled to any bonus?
Employees whose Basic Salary + DA exceeds ₹21,000 per month fall outside the mandatory coverage of the Payment of Bonus Act, 1965. For such employees, bonus is not a statutory right under central labor law, but rather a contractual entitlement governed entirely by the terms of their employment contract, offer letter, or company annual incentive scheme. If the offer letter specifies an annual target bonus or performance incentive, the employer cannot arbitrarily deny it without objective evaluation.
3. Can a company forfeit my bonus if I resign before the Diwali bonus payout date?
If you are an eligible employee (Basic ≤ ₹21,000 and served at least 30 working days in the accounting year), the company cannot forfeit your statutory bonus simply because you resigned before the disbursement date. You are entitled to pro-rata statutory bonus for the period served. However, for discretionary performance bonuses or ex-gratia incentives outside the statutory ceiling, companies often enforce an “active employment on payout date” clause which labor courts have upheld for non-statutory incentives.
4. What legal action can an employee take if an employer refuses to pay statutory bonus?
Under Section 21 of the Payment of Bonus Act, an employee or their authorized agent can make a formal application to the State Labor Commissioner or appropriate government authority within 1 year from the date the money became due. The government authority will issue a certificate of recovery to the District Collector, who recovers the unpaid bonus as arrears of land revenue. Additionally, employers contravening the Act face imprisonment up to 6 months and statutory fines under Section 28.
5. Are probationers and contract workers eligible for statutory bonus?
Yes. The definition of an “employee” under Section 2(13) includes any person employed on wages to do manual, technical, clerical, or supervisory work. It makes no distinction between permanent, probationary, temporary, or contract employees. As long as a probationer has worked for a minimum of 30 days in the accounting year and earns ₹21,000 Basic or less, they are legally entitled to statutory bonus on a pro-rata basis under our probation period rules guide.